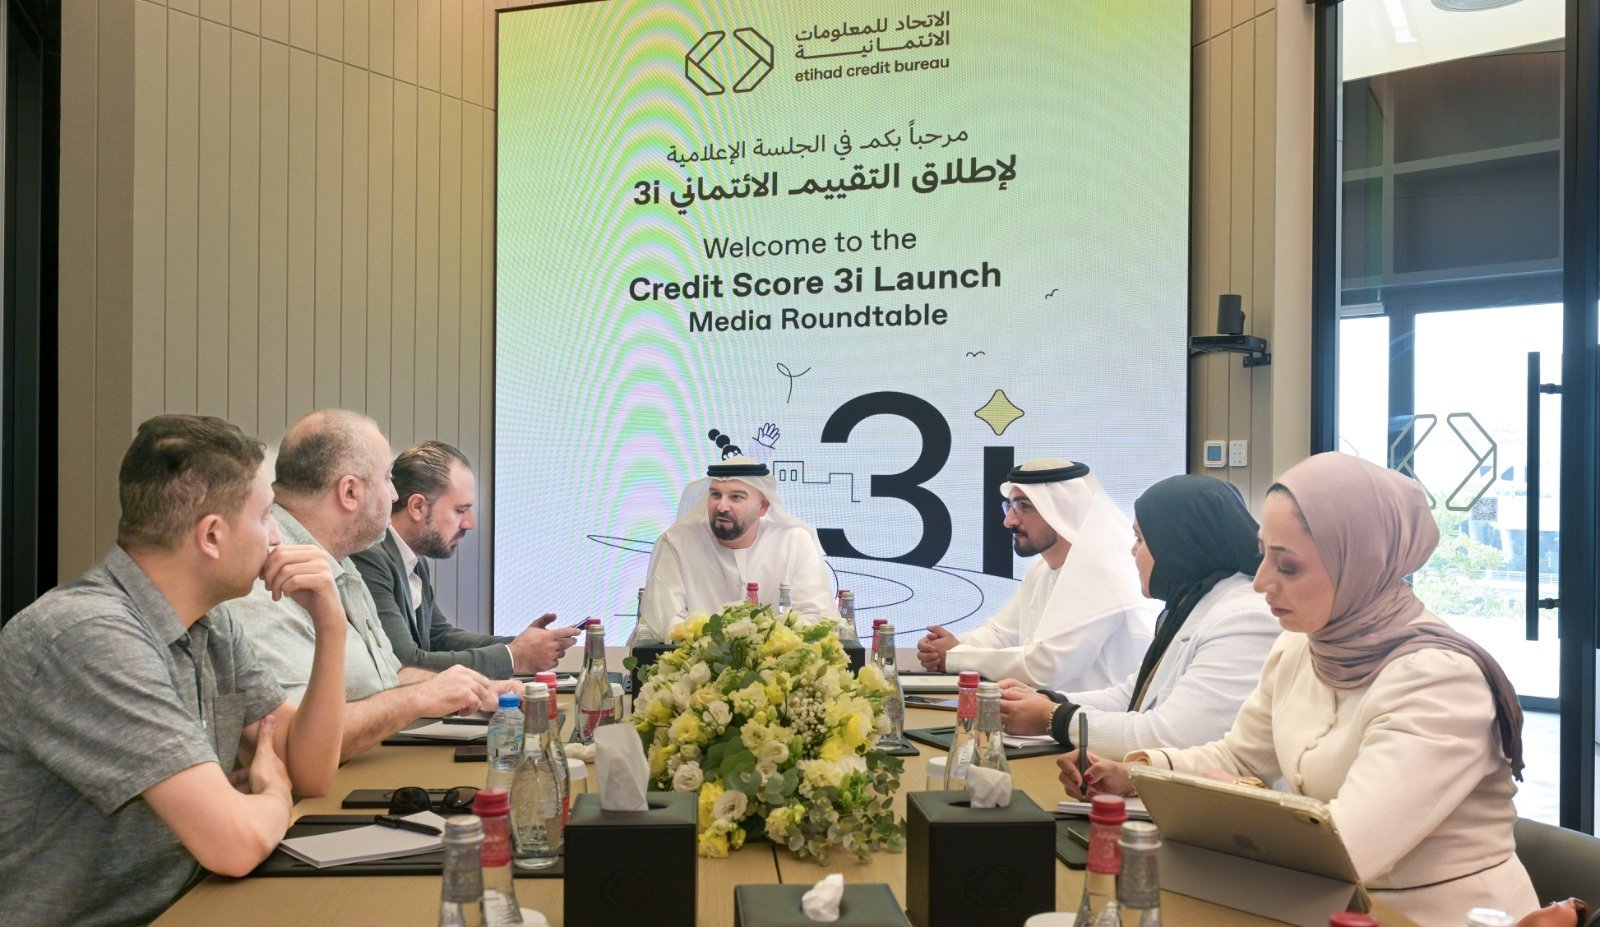
Etihad Credit Bureau, the federal entity responsible for providing credit information and data-driven analytics in the UAE, has announced the launch of its next-generation Credit Score 3i for individuals at its new Abu Dhabi office. The launch represents a significant evolution in credit scoring methodology, reflecting the evolving financial landscape and the increasing diversity of credit products and consumer borrowing patterns in the UAE.
The enhanced model assesses individuals’ credit behaviour over a period of up to 36 months, compared to 24 months under the previous model, drawing on a broader range of indicators related to financial obligations and repayment patterns. This extended assessment period provides a more comprehensive view of how credit behaviour evolves over time, supporting a better understanding of credit profiles and more informed risk assessments.
Beyond the extended assessment period, the new model also enables the assessment of eligible new-to-credit individuals and new to country who have limited credit histories. It uses two distinct scoring models tailored to cater two different customer segments based on the length of their credit history.
The enhanced model benefits individuals with established credit histories, as well as eligible individuals who are new to credit and recent residents of the UAE with limited credit histories. It helps them better understand the factors influencing their credit profiles, monitor their financial obligations and make more informed financial decisions.
For banks, financial institutions and other authorised entities, including eligible fintech companies and digital platforms, the enhanced model provides more comprehensive credit information and indicators to support risk assessment and credit decisions. Its insights may also support the needs of government and regulatory entities, as well as the SME, entrepreneurship and real estate sectors, subject to each entity’s mandate and applicable data access requirements. Lending decisions remain subject to the policies and assessment criteria of individual lenders.
The launch of Credit Score 3i builds on more than a decade of work by Etihad Credit Bureau to develop the UAE’s credit information ecosystem, since the Bureau commenced operations and issued the country’s first credit report. The model responds to the growing volume of credit data and the increasing diversity of financial products and services in the UAE.
H.E. Marwan Ahmad Lutfi, Director General of Etihad Credit Bureau, said: “The UAE continues to develop its financial and credit information ecosystem in step with economic and technological change. Credit Score 3i advances the use of data and analytics to support more comprehensive credit risk assessments, strengthen financial sector efficiency and encourage responsible credit practices.”
He added: “The new model provides deeper insights into individuals’ credit behaviour over longer periods and extends credit scoring to additional eligible segments. It introduces two scoring ranges: 300–850 for individuals with established credit histories and 300–650 for eligible individuals with limited credit histories. This helps individuals better understand their credit profiles and supports lenders in making informed decisions and managing risk more effectively.”
He emphasised: “The new model analyses positive practices, recognises sustained improvements in credit behaviour, and reflects these improvements in the score within six months after defaults have been settled. Through the credit report, it also provides an analysis of the factors influencing the score, whether positive or negative, and offers users a number of recommendations that may help improve their score if followed. These updates help individuals gain a clearer understanding of their credit profiles, enabling them to make responsible financial decisions and adopt positive financial behaviours.”
One of the key enhancements of Credit Score 3i is its ability to recognise improvements in credit behaviour and potentially reflect them in individuals’ credit scores sooner. Following the resolution of defaults, consistent repayment of financial obligations and responsible credit practices may lead to an improvement in an individual’s credit score within six months, depending on their subsequent credit behaviour, overall credit profile and the model’s criteria. However, an increase in the credit score during this period is not guaranteed. New defaults or other negative developments affecting an individual’s credit history may also impact any progress made, requiring a further period of positive credit behaviour before improvements can be reflected in the score.
Credit Score 3i introduces two scoring ranges based on customer categories. The first ranges from 300 to 850 for individuals with established credit histories, while the second ranges from 300 to 650 for eligible individuals who are new to credit or new to the UAE and have limited credit histories.
The enhanced model also encourages greater awareness of the importance of timely repayments and responsible management of financial obligations. At the same time, it provides lenders and other authorised entities with more comprehensive credit information and insights to support lending decisions and risk management, in accordance with each institution’s established policies and criteria for assessing repayment capacity.
